Learning Outcomes for the Professional Competence of an Engagement
Partner
Engagement Partner to develop and maintain professional competence that is demonstrated by the achievement of learning outcomes including, but not limited to, those listed under the competence areas below:
- Evaluate whether an entity has prepared, in all material respects, financial statements in accordance with the applicable financial reporting framework and regulatory requirements.
- Evaluate the recognition, measurement, presentation, and disclosure of transactions and events within the financial statements in accordance with the applicable financial reporting framework and regulatory requirements.
- Evaluate accounting judgments and estimates, including fair value estimates, made by management.
- Evaluate the fair presentation of financial statements relative to the nature of the business, the operating environment, and the entity's ability to continue as a going concern.
Application of Financial Reporting Standards in Lao PDR
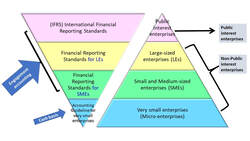
The Law on accounting n°47/NA 26 December 2013, distinguishes two categories of enterprises to prepare their financial statements: public interest enterprises and nonpublic interest enterprises.
To be complied with the socio-economic context of Lao PDR that comprises many sizes of non-public interest enterprises and to facilitate each enterprise size to apply financial reporting standards appropriate to its size, the Ministry of Finance divides non-public interest enterprises into
To be complied with the socio-economic context of Lao PDR that comprises many sizes of non-public interest enterprises and to facilitate each enterprise size to apply financial reporting standards appropriate to its size, the Ministry of Finance divides non-public interest enterprises into
- Large-sized enterprises (LEs),
- Small and medium-sized enterprises (SMEs), and
- Micro-enterprises.
International Financial Reporting Standards (IFRS)
Public interest enterprises shall apply International Financial Reporting Standards (International Financial Reporting Standards, IFRSs).
Learn more IFRS/IAS
Learn more IFRS/IAS
Lao Financial Reporting Standards (LFRS)
Non-Public interest enterprises which are large-sized enterprises and small and medium-sized enterprises, shall apply Financial Reporting Standards for non- Public interest enterprises which are divided into two parts such as for large-sized enterprises (refer as to financial reporting standards for large-sized enterprises, FRS for LEs) and for small and medium-sized enterprises (refer as to financial reporting standards for small and medium-sized enterprises, FRS for SMEs).
Accounting Guideline for Micro Enterprise
Very small enterprises shall apply Accounting Guideline for very small enterprises under which transactions and other events are recognized when cash or its equivalent is received or paid.
We are delighted to share with you two integrated reporting resources that recently launched alongside the IFRS Sustainability knowledge hub:
A mapping tool showing one possible way to incorporate ISSB disclosures within an integrated report
Updated FAQs covering the relationship between the Integrated Reporting Framework and the ISSB Standards and other frameworks and standards in the corporate reporting landscape
These resources are designed to help integrated report preparers apply the ISSB Standards from next year.
The ISSB Standards can help companies populate integrated reports with standardised and comparable, investor-focused information. IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information incorporates concepts from the Integrated Reporting Framework. Both acknowledge that companies do not operate in a vacuum. The relationships between a company and its surrounding stakeholders, society, environment and natural environments can—through dependencies and impacts—give rise to sustainability-related risks and opportunities that can affect the resources and relationships (capitals) on which a company relies or has an impact. Furthermore, the Integrated Reporting Framework and the ISSB Standards share the same target audience—primary users of general purpose financial reports—and acknowledge the importance of connected information.
The IFRS Sustainability knowledge hub is a key component of the IFRS Foundation’s capacity building programme. It hosts IFRS Foundation content, as well as more than 100 resources developed by third-party organisations. Materials will be added over time in response to market needs and emerging practices.
To stay updated on the latest IFRS Sustainability news and resources, as well as the ISSB’s work and opportunities to get involved, subscribe for news alerts.
https://www.ifrs.org/sustainability/knowledge-hub/?utm_medium=email&_hsmi=285424452&_hsenc=p2ANqtz-_SaO0WThtj-DhW9MpAqzycvCf9Jni1V4cmesyovNL8tJmg_jW886U1GXCgW6aSmh0JluMNy9OnWwgEwgKxxSkU4t3b9Q&utm_content=285424452&utm_source=hs_email
A mapping tool showing one possible way to incorporate ISSB disclosures within an integrated report
Updated FAQs covering the relationship between the Integrated Reporting Framework and the ISSB Standards and other frameworks and standards in the corporate reporting landscape
These resources are designed to help integrated report preparers apply the ISSB Standards from next year.
The ISSB Standards can help companies populate integrated reports with standardised and comparable, investor-focused information. IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information incorporates concepts from the Integrated Reporting Framework. Both acknowledge that companies do not operate in a vacuum. The relationships between a company and its surrounding stakeholders, society, environment and natural environments can—through dependencies and impacts—give rise to sustainability-related risks and opportunities that can affect the resources and relationships (capitals) on which a company relies or has an impact. Furthermore, the Integrated Reporting Framework and the ISSB Standards share the same target audience—primary users of general purpose financial reports—and acknowledge the importance of connected information.
The IFRS Sustainability knowledge hub is a key component of the IFRS Foundation’s capacity building programme. It hosts IFRS Foundation content, as well as more than 100 resources developed by third-party organisations. Materials will be added over time in response to market needs and emerging practices.
To stay updated on the latest IFRS Sustainability news and resources, as well as the ISSB’s work and opportunities to get involved, subscribe for news alerts.
https://www.ifrs.org/sustainability/knowledge-hub/?utm_medium=email&_hsmi=285424452&_hsenc=p2ANqtz-_SaO0WThtj-DhW9MpAqzycvCf9Jni1V4cmesyovNL8tJmg_jW886U1GXCgW6aSmh0JluMNy9OnWwgEwgKxxSkU4t3b9Q&utm_content=285424452&utm_source=hs_email